

Mi Technovation Bhd, the Penang-based semiconductor equipment maker listed on Bursa Malaysia, is spinning off its solder sphere business onto the SGX Mainboard. Mi Material is headquartered in Singapore, with production in Taiwan and China. Mi Material Holding is targeting a 28 October debut at an indicative S$1.80 a share, valuing it at about S$891 million.
The headline numbers are striking. First-half revenue doubled, and profit rose roughly fivefold. Tech listings are rare, and this one lands just as AI is all the rage. Is it an IPO to watch, and to apply for?


What does Mi Material do?
A chip needs electrical connections to receive power and signals, but it is far too small to be wired straight to the circuit board (PCB) it sits on. That is where solder spheres come in. Think of a semiconductor chip as the engine of an F1 car. It may be extraordinarily powerful, but without reliable connections to the rest of the car, such as the wheels, that power is useless. Solder spheres serve a similar function. They form the electrical pathways that carry power and signals between a chip package and the circuit board.

Mi Material makes these spheres in sizes from 0.030mm to 0.889mm across. As chips become more powerful and densely packed, these connections must withstand greater heat and mechanical stress. The spheres may be small and inexpensive relative to the finished device, but failure can compromise a chip or system worth many times more.

Mi Material sells these high-volume semiconductor consumables to chip packaging companies. Revenue grows with customers’ production volumes, while the increasing contribution from proprietary specialty alloys supports higher selling prices and margins. Lengthy qualification cycles make supplier changes difficult, creating recurring demand once a product is approved. Growth therefore depends on securing qualifications, increasing the value of the product mix and adding capacity to meet customer demand.
The business started in Tainan, Taiwan in 1998 under the Accurus brand. Henkel owned it from 2006 to 2010, management bought it back, and Mi Technovation bought it in 2021.

According to Yole, the market researcher the company commissioned for the prospectus, Mi Material held 24% of the global solder sphere market it can serve in 2025, putting it in the top three worldwide. Its main competitors are Senju Metal of Japan, Duksan Hi-Metal and MK Electron of Korea, and Shenmao of Taiwan.
Its edge is in specialty alloys. Its patented Cyclomax and iSAC spheres sell at higher prices than standard tin-silver-copper (SAC) spheres because they hold up better under heat and stress. These two lines rose from 33.8% of revenue in FY2023 to 59.9% in the first half of 2026. Cyclomax revenue alone grew 168% year on year.
That edge is hard to copy. A new competitor cannot simply make an equivalent solder sphere and win the business. Customers put every new supplier through lengthy testing before a material can enter mass production. Mi Material’s prospectus puts this at 12 to 24 months, and two to five years or longer for the most demanding advanced packaging. Once a product is qualified, customers have little reason to switch without a compelling one, because a change of material could mean fresh testing and new reliability risks. Know-how also builds up with each product generation, which makes the gap harder for a newcomer to close.
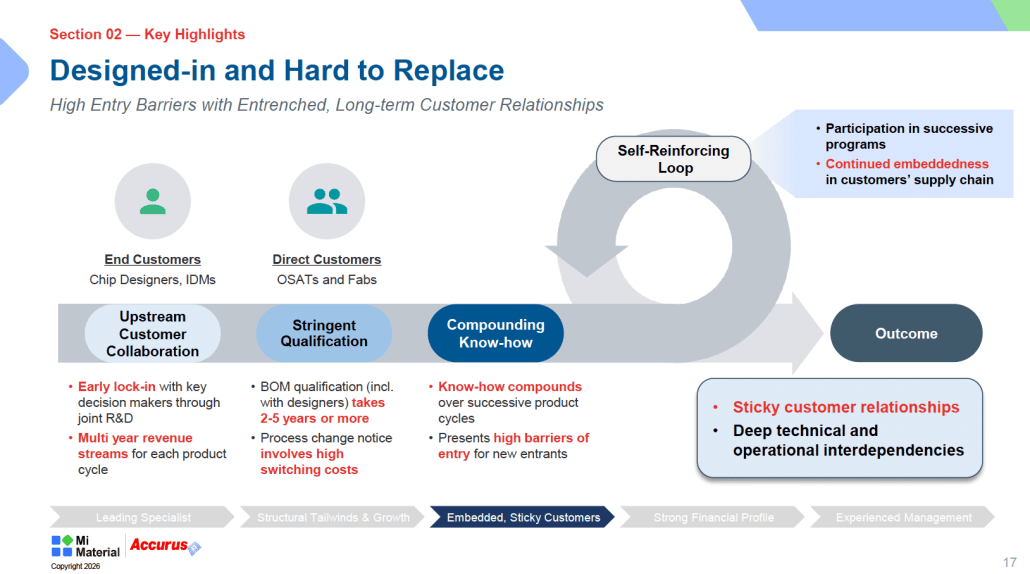
Mi Material’s tailwinds and sector exposure

About three-fifths of revenue comes from phones and wearables. High-performance computing (HPC) and memory, where AI demand shows up, is about a third, and its share has risen only slowly.
The customer list confirms this. Most sales go through chip packagers, but the prospectus identifies three end-customers that drive demand:
- Customer X (24% of 1H 2026 revenue), described as a company best known for premium consumer electronics, an OS and services ecosystem, and an iconic retail presence.
- Customer Y (18%), best known for ASICs used in AI, plus enterprise software and networking.
- Customer Z (16%), a NAND memory maker.
Together these three account for 58% of revenue, up from 43% in FY2023. Concentration risk is present, but the prospectus also warns that buyers in this market are few and large, which gives Mi Material pricing leverage.
The AI angle is genuine and growing through Customers Y and Z. Yole expects HPC and memory to grow from 25% to 35% of the serviceable market by 2031. But today, this is mainly a premium smartphone supplier with a growing AI business, not the reverse.
The Numbers
| US$ million | FY2023 | FY2024 | FY2025 | 1H 2025 | 1H 2026 |
| Revenue | 39.8 | 46.8 | 65.3 | 25.6 | 53.7 |
| Gross margin | 36.0% | 41.0% | 36.3% | 37.3% | 45.9% |
| Net profit | 4.1 | 8.2 | 10.0 | 2.9 | 14.3 |
| Adjusted net profit | 3.8 | 7.4 | 10.5 | 4.1 | 14.3 |
| Adjusted EBITDA | 8.2 | 13.3 | 16.7 | 6.5 | 20.1 |
| Operating cash flow | 5.5 | 11.3 | (0.9) | (1.6) | (5.4) |
Mi Material looks to surpass its FY 2025 revenue, as its 1H 2026 revenue has already clipped the US$53 million mark.
Gross margins are also lifted by higher prices from passing on tin, silver and copper costs. The company does not hedge its metals. When metal prices spiked in 2025, it could not pass costs fast enough, and gross margins fell from 41.0% to 36.3%. According to private markets research house pvtIQ’s notes from management, prices are now reset monthly, and metals are bought weekly, which limits unhedged exposure to about one week. Prices are held only while metal prices stay within 5.0% of the baseline.
Profits have yet to translate into positive cashflow. Despite a pre-tax profit of US$18.5 million in 1H2026, operating cash flow was negative US$5.4 million. Working capital absorbed US$23.5 million. Receivables rose US$12.6 million, inventory US$8.2 million, and advance payments for metal US$3.4 million. Short-term bank borrowings rose from US$13.0 million to US$22.3 million.
Capacity is the constraint
The company runs 19 production lines: 13 in Taiwan and six in Ningbo, China. Taiwan ran at 80% to 85% utilisation in the first half. Ningbo ran at only 10% to 15%.
Ningbo’s challenge is regulatory. China has required export licences for silver since the start of 2026. According to management, its silver-containing spheres were treated as silver products and the company did not get a licence, so Ningbo cannot serve export customers and is being repositioned for the domestic market. The prospectus also discloses a customs fine, already paid, for exporting bismuth-containing products without a license, and a separate customs finding that 52 export shipments were misclassified. The maximum penalty for that case is RMB8.8 million (about US$1.2 million). It is not material to earnings, but it shows the China plant is not a growth asset for now.
The growth now depends mostly on its new plant in Senai, Johor. Phase 1 has three lines ready for production in the fourth quarter of 2026, ramping up in early 2027. Phase 2 comes with four more lines, operational by end 2027, with ramps up in 2028.
The Deal
| Shares | At S$1.80 | |
| New shares (public offer and placement) | 51.5m | S$92.7m |
| Cornerstone shares (new, separate from the offer) | 41.9m | S$75.4m |
| Gross proceeds to the company | 93.4m | S$168.2m |
| Vendor shares sold by Mi Technovation | 26.0m | S$46.8m |
| Total shares sold | 119.4m | S$214.9m |
After fees, the company receives about S$157.9 million. There will be about 495 million shares outstanding, with Mi Technovation keeping about 73.7%. An over-allotment option of up to 5 million more vendor shares supports stabilisation in the first 30 days.
The seven cornerstone investors are abrdn Asia, abrdn Malaysia, Amova Asset Management, Areca Capital, Barings Singapore, Fullerton Fund Management and Manulife Investment. They are not subject to any lock-up. Their 41.9 million shares, about 8.5% of the company, can be sold from the first day of trading. Mi Technovation and its key individuals have agreed to lock-ups.
The largest use of the money is not the Malaysian plant. That was already planned before the IPO. Most of the funds raised will be for US expansion and the Taiwan plant refurbishment.
| Use of gross proceeds | S$ million | Share |
| R&D and demonstration centre in Texas, US | 55.8 | 33% |
| Taiwan plant refurbishment and upgrades | 33.3 | 20% |
| Malaysia plant expansion | 27.9 | 16% |
| Singapore R&D laboratory | 23.0 | 14% |
| Working capital | 17.9 | 11% |
| Fees and expenses | 10.3 | 6% |
The Texas centre, due by end-2028, will start with two automated lines and could become a full plant. The logic is that many customers run their R&D and qualifications from the US. The US punt is not a straightforward win, as most of the packaging business sits in Asia.
Nevertheless, with chips slowly becoming a proxy for warfare, it’s no harm to have a presence in both Asia and the US.
Singapore gets a share of the money too. About S$23.0 million, or 14% of the gross proceeds, is set aside for a new R&D laboratory here. It will focus on electromigration studies and complementary products such as thermal interface materials, with about 40 R&D and technical staff. Mi Material also plans collaborations with leading professors by early 2027.
Valuation
| Earnings basis | Net profit (US$m) | P/E |
| FY2025 actual | 10.0 | ~70x |
| 1H 2026 annualised | 28.6 | ~24x |
| FY2026 estimate | ~35 to 37 | ~19 to 20x |
| September-quarter run-rate, annualised | ~42 to 46 | ~15 to 17x |
While FY2026 is not yet crystalised, based on guided revenue and gross margin, a reasonable estimate for FY2026 would land net profit around US$ 35 to 37 million, giving an implied 19-20x P/E ratio.
It does not look expensive next to its peers. The median forward P/E of Singapore advanced manufacturing stocks is at 29.8x.

But on the sales perspective, Mi Material trades at around 5.4x estimated FY2026 revenue, putting it far above listed solder makers. The price over sales and earnings diverged due to Mi Material’s margins, which are much higher than those of its peers. A 26.6% net margin earns a P/E discount but inflates the price to sales.
If the margin superiority is the moat, then the P/E holds ground. If margins can and contract in the future, there will be a re-rating.
Verdict
Mi Material commands a sizable share of the solder market. It is priced below most Singapore semiconductor stocks.
It is still growing, in the right business model, but its profits are not translating into cash.
The US centre is a reasonable punt, but its fate still rests on its major customers. The idle China plant is worth noting, even if it might not make or dent the overall financials.
The questions to answer before applying: will September-quarter margins hold through a metal price swing, will cash flow turn positive as growth settles, and will Senai qualify on time?
Disclosure: This article is sponsored by SGX. The article reflects the author’s personal opinion and does not constitute financial advice.


